x

Your Car Insurance Doesn't Cover What You Think It Does

(NewsUSA) - You have car insurance, pay your premiums and assume you're protected if an accident happens. But what if the coverage you rely on isn't enough to pay for a serious injury?

For many drivers, the difference between what their insurance policy covers and what an accident actually costs could leave them facing thousands of dollars in unexpected expenses.

In Texas, drivers are required to carry liability insurance, but the state's minimum coverage requirements haven't increased since 2011, even as medical expenses and other accident-related costs continue to rise.

The $30,000 Coverage Gap

Under Texas law, drivers must carry minimum liability coverage of $30,000 for injuries to one person, $60,000 for injuries per accident and $25,000 for property damage. Known as 30/60/25 coverage, these amounts represent the legal minimum, not necessarily the protection needed after a serious crash.

According to a 2023 report from the National Highway Traffic Safety Administration (NHTSA), the estimated average lifetime medical cost of a serious crash injury was $69,345, while the total economic cost reached $280,726, based on 2019-dollar estimates.

That total economic cost is more than nine times Texas's $30,000 minimum bodily injury liability limit.

The problem? Once the at-fault driver's liability insurance reaches its policy limit, that coverage generally won't pay additional expenses, even when medical bills, lost income and rehabilitation costs continue to grow.

When the Other Driver Doesn't Have Enough Insurance

The financial risk becomes even greater when the driver responsible for an accident has little or no insurance.According to research cited by the Insurance Research Council, approximately one-third of U.S. drivers were uninsured or underinsured in 2023.That means even when another driver is responsible for a collision, their insurance coverage may not be sufficient to compensate everyone injured.

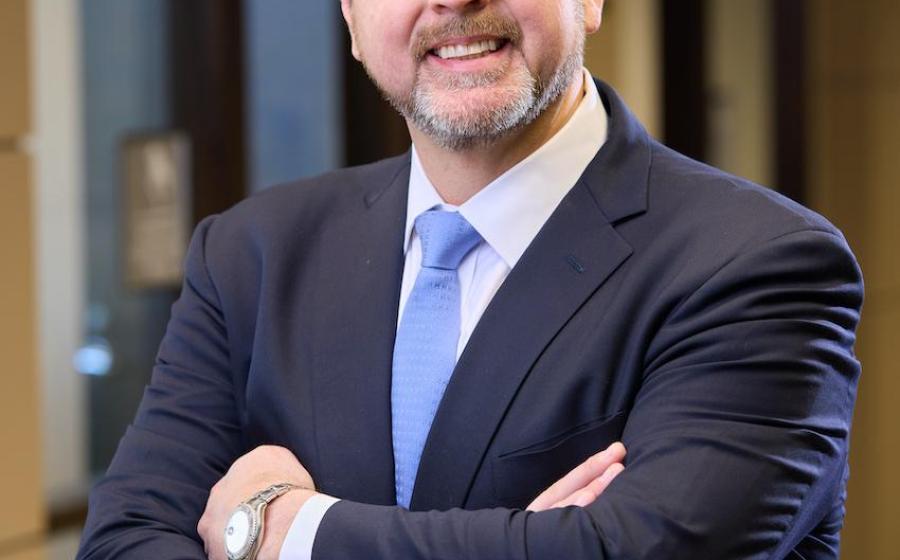
Ryan L. Thompson, founder and managing partner of Thompson Law, also known as 1-800-LION-LAW, understands these challenges from both sides of the legal process. Before representing injured individuals, Thompson spent years defending major corporations, gaining firsthand experience with how insurance claims are evaluated and resolved.

The Coverage Many Drivers Overlook

One important protection is uninsured and underinsured motorist coverage, commonly known as UM/UIM.

This coverage can help eligible policyholders recover certain expenses when an at-fault driver has no insurance or insufficient liability coverage.

Texas law generally requires insurers to include UM/UIM coverage in auto policies unless the policyholder rejects it in writing.

However, drivers may decline this protection to reduce their premiums without fully considering the potential financial consequences.

Understanding the difference between liability coverage and UM/UIM protection is an important step toward avoiding costly surprises.

Check Your Policy Before an Accident Happens

Thompson Law encourages drivers to review their insurance declarations page, which summarizes their coverage types, limits and deductibles.

Drivers should check whether their liability limits are adequate, whether they carry UM/UIM coverage and whether additional protection makes sense for their circumstances.

The Dallas-based personal injury firm, founded by Thompson, reports recovering more than $2.1 billion for injured people and families nationwide as of August 2026.

The message for drivers is simple: Meeting the state's minimum insurance requirements doesn't necessarily mean you're fully protected.

Taking a few minutes to understand your policy today could make a significant financial difference tomorrow.

For more information, visit 1-800-LION-LAW.com.
5 Insurance Company Tactics That Could Shrink Your Injury Claim

(NewsUSA) - After a car crash, dealing with injuries, medical appointments and vehicle repairs can be overwhelming enough. Then comes another challenge: dealing with insurance companies.

While consumers may expect an insurer to simply determine what happened and pay a fair claim, the claims process can be much more complicated. Adjusters may request recorded statements, seek broad access to medical records or make settlement offers before the full extent of an injury is known.

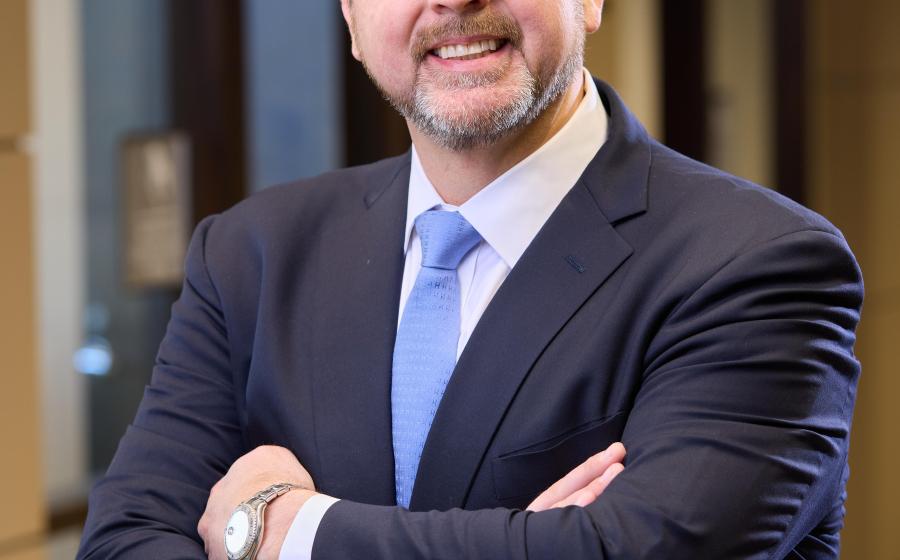
Ryan L. Thompson, founder and managing partner of Thompson Law, says injured consumers should understand how the claims process works before making decisions that could affect their recovery. Thompson previously defended corporations before establishing his personal injury practice, giving him experience with how insurers and defense teams evaluate and resolve claims.

Here are five issues consumers should watch for after an accident.

1. The recorded statement

Soon after a crash, an insurance adjuster may ask an injured person to provide a recorded statement about what happened and how they are feeling.

In Texas, a participant in a telephone conversation generally may record that conversation without obtaining the other participant’s permission. Consumers should therefore assume an insurance call may be recorded rather than assume a conversation is off the record.

That distinction matters when injuries are still developing. Someone who says they feel “fine” shortly after an accident may later discover an injury that was not immediately apparent.

There is also an important difference between dealing with your own insurer and the other driver's insurer. A standard Texas personal auto policy contains a duty to cooperate with your own insurance company. Thompson cautions that an injured third party does not have the same contractual obligation to provide a recorded statement to the other driver's insurer.

2. The fast settlement offer

A quick check can seem like welcome news when medical bills and other expenses are mounting. But speed is not necessarily the same thing as a complete and fair evaluation of a claim.

The danger is settling before doctors know the extent of an injury or how long recovery may take. Once a claimant signs a release and resolves the claim, the opportunity to seek additional compensation for that claim generally ends.

Texas insurance law also addresses claim investigation. Thompson notes that Texas Insurance Code Section 541.060 prohibits an insurer from refusing to pay certain claims without conducting a reasonable investigation and requires good-faith settlement efforts in specified circumstances when liability has become reasonably clear. The statute does not specifically prohibit an insurer from making an early offer simply because an injury has not fully resolved.

The practical lesson: understand what is being settled before accepting an offer.

3. Broad access to your medical history

Another document to examine carefully is a medical-record authorization.

An authorization may give an insurer access to medical information extending beyond treatment directly connected to the accident. That can include older conditions or treatments that may become part of the insurer's evaluation of whether an injury resulted from the crash.

Thompson said nothing in Texas law requires an injured third party to provide the other driver's insurer with unlimited access to medical records. Consumers may instead limit an authorization by provider and date or offer to supply relevant records directly.

Read an authorization carefully before signing it and understand exactly what information it permits the recipient to obtain.

4. Computer-assisted claim valuation

Technology can also play a role in determining what a claim is worth.

In 2010, Allstate reached a multistate regulatory settlement involving the insurer's use of the Colossus claims-handling software. The insurer agreed to a $10 million regulatory settlement and reforms governing how the software was used. Among other provisions, the settlement addressed notice to claimants and prohibited requiring adjusters to settle claims solely according to a value recommended by the software.

The historical case should not be interpreted as proof that insurers today systematically underpay claims using software. New York's insurance superintendent said the examination did not find systemic underpayment of bodily-injury claims.

For consumers, the broader point is that a claim may involve standardized valuation tools as well as human judgment. Medical documentation, lost wages and the individual circumstances of an injury can therefore be important in establishing the full picture.

5. Delay and repeated requests

Finally, keep track of what happens after a claim is opened.

Dates, phone calls, documents submitted and the names of adjusters can become important if a claim stalls. Keep a simple log of every call, adjuster's name and date.

Some Texas claims involving a person's own insurer are also subject to statutory deadlines.  The consumer must distinguish those deadlines from third-party claims involving the other driver's insurer, an important difference consumers should understand rather than assuming the same timetable applies to every claim.

Keeping copies of correspondence and maintaining a timeline can help consumers know what information has already been supplied and what remains outstanding.

Know what you're agreeing to

Thompson Law handles vehicle crashes and other serious personal injury and wrongful-death cases. The Dallas-headquartered firm, with additional Texas offices in San Antonio, Houston and Waco, says it has recovered more than $2.1 billion for injured people and families as of August 2026.

For Thompson, the takeaway for injured consumers is simple: don't treat every request from an insurance company as routine paperwork. Understand what information is being requested, what rights may be affected, and what accepting or signing a document means before making a decision.

More information is available from Thompson Law / 1-800-LION-LAW or 1800lionlaw.com.

Subscribe to Insurance