x

Our first spending approval process lasted six weeks

Our first spending approval process lasted six weeks

(Jens Hagel) - The list that replaced it is still running, and it changed how I ask my team about odd costs on the account.

Edited by Jenn Moon, Editor at Featured News · Nov 16, 2026

I ran an IT service company in Hamburg, Germany. When we first tried to keep track of spend, we had a multilevel approval workflow. A purchase request was entered at the bottom and exited, signed, at the top.

It worked for about six weeks. After that, half of all purchases were made without using it. Nobody was being sneaky about it. When you need to buy something, you want it done quickly. A request that needs to be signed by someone takes longer. If you have a process that can be avoided, people may avoid it.

Where the workflow failed

The levels were probably not the biggest problem. By putting the workflow in front of the purchase, you miss information you only have after the purchase is made. Do you still use this tool? Does anyone know who is using it? Is it more expensive than it used to be? None of these questions can be answered before a purchase is requested.

Small recurring spend is a good example. We looked at our list of small recurring spend and found 11 items. Each cost between €4 and €38 per month, totaling €214 per month. For seven of these items, we could not say why we had purchased them. I don't believe we would have caught any of them if we had an approval workflow in place. Each item probably seemed like a good idea when we first bought it.

List on a Friday

We created a list we would look at on a Friday. This is what we do today.

I believe it has lasted because it allows the person making the purchase to do what they need to do. Then on a Friday, we go through our list and compare it to our account statement. We are now asking questions about purchases a week later instead of not at all.

If I was setting this up today, I would have all purchases from last Friday to current on the list. Include any that you don't recognize. Keep it small enough to get through in one sitting. I would ask who is responsible for the purchase. We have learned this the hard way. We had a contract that renewed for a year. There was a reminder to cancel the contract, but it was in someone's calendar who no longer worked for us.

Unusual is a question

When I look at something unusual on my account statement, I ask a question. Usually, there is a simple explanation. Billing changed to a different day of the month or a trial we forgot to cancel. If you start to look at every unusual item as suspicious, you might never find out what is really going on.

When you do find something that isn't simple, you want to know. According to the Association of Certified Fraud Examiners (ACFE) in their 2026 Report to the Nations, 43% of the occupational fraud cases studied were detected through tips. That is almost three times the next highest method. More than half of those tips came from employees. I think that if you have a company culture where you ask questions about money, your employees will be more comfortable reporting.

We took this into Yupana when we created our software. We ran our checks on unusual bookings against our own data. Before we allowed anyone to be alerted, we looked at all 548 results. You don't want to create a check that alerts on too many things. People will learn to ignore it, and you are back where you started.

Where this method fails

This is my opinion based on my experience running one company. It may not work for you. A list on a Friday may not catch big one-time purchases. Or maybe a contract you should have known about before you signed it. You should have an approval workflow for those types of purchases. There are also companies that require you to separate purchasing from paying.

I think it takes about an hour to go through the list. If you have 10 employees, that is an hour of someone's time. I would still do it. Those 11 recurring expenses totaled €214 a month, or €2,568 a year.

The same ACFE study found that over half of the fraud they studied occurred because of missing internal controls or someone bypassing them. Having a list that your team goes through with good intent is not going to prevent that. You also need someone to remember to look at it.

About the author

Jens Hagel

Jens Hagel is co-founder of Yupana, software for mid-sized companies that brings bank transactions, contracts, software licenses and the monthly management report together in one view. In 2004 he founded an IT services company in Hamburg, Germany, and ran it for more than 20 years. He writes about spending and controls in small firms.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

I spent months comparing banking software before I could name the problem

I spent months comparing banking software before I could name the problem

(Jens Hagel) - The fix took 15 minutes, and it changed the order in which I look at any new tool for our finances.

Edited by Jenn Moon, Editor at Featured News · Nov 13, 2026

We spent months talking about switching our banking software. I had an IT service company in Hamburg, Germany, for over 20 years. At some point, the program we were using for our payments and bank statements started becoming the bottleneck. We researched and did demos like most small companies do.

In the end, we stayed with the same program. The problem we actually had was much smaller. Our bank statements were in that program and no other system in our company could access them. We exported them to a network drive on a daily basis in cash management (CAMT) format, which is commonly used for electronic bank statement files in Europe. Our other programs could then read these files. The solution took 15 minutes.

I think about this often. It's such a simple mistake. We researched software before we identified the problem we had. I believe this is the most costly way to do things.

Regret is common

Research shows that as well. Capterra surveyed financial services companies in their 2025 Tech Trends report. 70% of respondents had regrets about a software purchase in the last 18 months according to Accounting Today in 2025. The most common product-related reason among respondents who regretted a purchase was that the software was too basic for their needs, at 35%.

I think this can happen when a customer says a piece of software is too basic. They may have found a need that they didn't list when purchasing the software. The software did what they were shown but no one identified what they needed it to do.

Write the question down first

Now when I'm looking at any software for my finance needs, I write the question that the software will answer. In one sentence and from the mouth of the person asking. In this case: Why can't I see what money came in and out of my bank account in my other programs? You would never look to buy a new bank program as the first answer to that question. Maybe an export.

You also know who should be in the room when testing this software out. If your bookkeeper is the one asking that question, have them test it out and the person that will be purchasing the software. Usually two different people in small companies.

My company had a similar question with our numbers a few years later: What am I paying for each month and why? There were answers in four different locations: our bank statements, our document storage program, our Microsoft account and our monthly report from our tax advisor. We had subscriptions to things we no longer used and software licenses for people who had left the company. All of these were correct programs to store that information. But the question wasn't answered in any one of them. Which led to the software I build today.

What are you paying for?

If you have that question written down, you can also look at the software you currently have. We had a piece of software that we paid for by user. For 2 years. We never had more than 6 users on it at any time. The vendor offered a cheaper option for this scenario. We never found out because no one asked. One call to the vendor would have solved that. No migration or training needed.

I would sit down with my current software once a year and do the same thing. If you can't answer a question with that software, call your vendor.

Use your own data

If you do decide that the software you're testing will solve your problem, test it with your data. A trial period will show you the software. It won't tell you if it will work with your data. Your account names and exports may not match what the vendor expects.

You'll spend more time the first week doing this. But that's the week you have the option to not buy the software.

When this won't work

This is my opinion from running my own company and helping others create software: There will be times that the program you have is the issue. Your vendor no longer supports the software or it doesn't meet your legal requirements. Writing down your question will help you figure that out too.

Some may say that you should have more than one question written down. I say have the question you know and let the other questions come.

About the author

Jens Hagel

Jens Hagel is co-founder of Yupana, software for mid-sized companies that brings bank transactions, contracts, software licenses and the monthly management report together in one view. In 2004 he founded an IT services company in Hamburg, Germany, and ran it for more than 20 years. He writes about finance and controlling in small firms.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

Interview with Steven Talia, Co-Founder & CEO, MY PRO: TRUSTED PROS

Interview with Steven Talia, Co-Founder & CEO, MY PRO: TRUSTED PROS

(Featured) - Talia discusses using AI for content, referrals and after-hours responses while measuring satisfaction, reviews and repeat business.

Edited by Haley Spracale, Editor at Featured News · Nov 13, 2026

What career experiences over your 20-plus years in support and executive roles led you to build a business focused on helping people find service professionals they can trust?

I’ve been fortunate to learn so much about building relationships and providing value to my clients. I’ve recognized the significant contributions I’m privileged to make in the lives of the individuals and families I work with. While some of that value is directly reflected in my interactions and the services I provide, a more consistent and equally impactful contribution is one that is likely an afterthought for most: providing referrals or recommendations for other professionals within and outside my specific industry. I’ve found that there is deep-rooted value in making a professional referral for one simple reason: trust. Trust is many things: comfort, confidence, peace of mind, and safety. It is also the primary metric and determining factor in why clients choose to work with you, come back to you, and recommend you to their closest friends and family.

You have described AI agents as a 24/7 “Chief of Staff.” What is one repetitive back-office task a service professional could delegate to AI first while keeping human oversight in place?

Website and SEO content. Give your Chief of Staff instructions just as you would to your strongest, most capable employee. Expect clear communication, feedback, and follow-through. You set the guardrails, approve the drafts, and your Chief of Staff executes. SEO and AI results rely on data that is available and accessible online. Allow your AI agents to research your competitors’ online traffic, keyword metrics, and visibility. Instruct them to update your web presence, improve your website, and add blogs using phrases your customers are searching for. Your Chief of Staff is capable of writing in your tone. Once you approve the drafts, it will post strategic blogs directly to your website, guiding traffic and AI search results to your website for answers.

Service businesses depend heavily on reputation and referrals. How can a business use AI to strengthen its word-of-mouth marketing without making customer communication feel automated or impersonal?

Word-of-mouth marketing is the strongest and most effective tool for any business because it homes in on the one factor that makes a difference: trust. Trust is passed along between consumers who have a relationship.

Nielsen's Trust in Advertising research found that 88% of people trust recommendations from people they know more than any other form of advertising.

Referred customers convert at roughly three to five times the rate of paid leads and stay about 37% longer.

Although 83% of consumers say they'd recommend a business after a great experience, only 29% actually follow through.

I believe word-of-mouth marketing should always be produced organically. However, a business can absolutely use AI to strengthen its word-of-mouth marketing without eroding the authentic, human touch. This can be done by using the technology to collect, organize, and strategically leverage customer feedback. A business pro can instruct AI agents to create personalized follow-up outreach for satisfied clients via email, using whichever CRM tool the business uses, with the business pro reviewing and approving each note before it goes out. These notes can thank clients for the opportunity to work with them. The call to action would be an invitation to recommend the business to a friend or promote it through a review and referral, where their endorsement reaches the people who already trust them.

What is one measure a service-business owner should track to determine whether an AI tool is genuinely improving the customer experience rather than merely saving time?

AI should improve efficiency and results. It should not supplant the human connection on which service businesses rely. For example, if you use AI to handle service requests and inbound calls after hours, the professional should respond to those customer communications directly and in a timely fashion. If customer satisfaction improves—as reflected in increased word-of-mouth recommendations, online reviews, and repeat business, and measured by retention and growth—that is one metric that can justify using AI tools. Ultimately, the customer experience is the driver. AI provides the autonomy to make communication and the customer experience seamless, regardless of the business’s hours of operation.

Thanks for sharing your knowledge and expertise. Is there anything else you'd like to add?

I invite everyone to leverage AI for their business needs. Also, always remember that no amount of machine learning can replace the value of a word-of-mouth recommendation. Trust is at the core of every relationship, both personal and professional. Leverage that trust effectively.

About the expert

Steven Talia, CFP®

Steven Talia, CFP®Co-Founder & CEO at MY PRO: TRUSTED PROS®

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

Interview with Arnab Ray, Entrepreneur, Mentor, Investor, Speaker and Author

Interview with Arnab Ray, Entrepreneur, Mentor, Investor, Speaker and Author

(Featured) - The entrepreneur discusses validation, product-market fit, pivots, funding discipline and weekly experiments through the lens of Evolutionary Entrepreneurship.

Edited by Jenn Moon, Editor at Featured News · Nov 13, 2026

Arnab, as an entrepreneur, mentor, investor and management consultant — and the author of the forthcoming Bloomsbury book, "Survival of the Smartest: Startups through the Lens of Evolution" — what perspective do you bring to helping founders understand why startups survive or fail?

With my experience over the last 18 years in the startup ecosystem — building ventures, mentoring entrepreneurs, observing startups and consulting with them — I’ve realized that some amazingly good ideas have failed, while ordinary ideas have given birth to amazing businesses.

One perspective I want to bring to founders about why startups survive or fail is that there is no monolithic approach: You don’t simply have a great idea, execute well, stick to your vision and remain relentless — the glorified, romanticized version of entrepreneurship we’re familiar with. That might work in extreme outlier situations, but in most cases, what you start as isn’t what you end up as.

Things change along the way. Markets change, your customers’ needs change, your competition changes, the economics change and technology changes. So the only way to survive is to adapt and evolve. I call this concept Evolutionary Entrepreneurship.

Looking back on nearly two decades of building ventures and advising more than 2,000 startups, what career experiences led you to view entrepreneurship through the lens of evolution?

We have seen several startups start as one thing and end up as something else. We have experienced this ourselves. We started as an small and midsize enterprise (SME) consulting firm called Array Consultancy Services and, based on market demands, gradually evolved into business planning (BPlan Experts), launched new ventures (PresentationGFX), pivoted from existing ones (iLogyx), and even shut down some (Vezume).

Over the past 18 years, we have attempted more than 17 ventures and had our fair share of successes, failures and consolidations. Today, we operate eight ventures in our portfolio. Through our portfolio of ventures, we have supported more than 2,200 startups, including 350+ that I have personally mentored or advised.

Throughout this journey, I have noticed that businesses often change their paths, products, target customers and even their entire business models as they learn what the market truly needs. And one question kept bothering me.

Entrepreneurial activity has definitely increased in several markets. According to India's Ministry of Commerce and Industry, the number of startups recognized by the Department for Promotion of Industry and Internal Trade (DPIIT) grew from 502 in 2016 to more than 223,000 by March 31, 2026. Global venture capital investment increased from around $71 billion in 2013 to over $354 billion in 2024, an almost fivefold increase. In India, venture investment grew from about $1.7 billion to $16 billion over the same period, an almost tenfold jump.

Barriers to entry for startups have decreased considerably in many sectors, such as tech, direct-to-consumer (D2C), product prototyping and marketing. Modern tools have made it considerably cheaper to build and launch products, and artificial intelligence (AI) has made the process faster. For example, Amazon S3 cloud storage prices fell from $0.15 per GB per month in 2008 to $0.023 in 2016, a reduction of approximately 85%.

Startup ecosystem support has also expanded considerably through government programs, grants, incubators, accelerators and mentorship networks. In India, the MeitY Startup Hub network included more than 517 incubators and 329 labs by December 2025. The Startup India Seed Fund Scheme also has a corpus of ₹9.45 billion to support early-stage ventures.

In the U.S., the five-year survival rate of new employer business establishments has remained around 50% over the past three decades. The five-year survival rates were 54.3% for the 1994 cohort, 49.8% for the 2006 cohort, and 57.3% for the 2018 cohort.

We see a lot of attempts at entrepreneurship, but that does not necessarily translate into successful and sustainable ventures. This perplexed me. Then I realized that the business and management concepts we have been using for startups have primarily been borrowed from the structured industrial era. But startups work in a very different way. In fact, startups work more like living organisms or species in an evolutionary environment than like a linear process in which one step follows another.

Your framework treats the market as an environment that selects among competing variations; what is one early, low-cost experiment founders can run to validate whether a customer problem is real?

I believe there are three kinds of validation a startup requires. The first, which I call research validation, is the weakest form. It involves understanding the market from behind a computer by researching the industry, the competition and the trends. That can give you a macroeconomic view of a startup, but it does not necessarily mean there is a genuine customer problem or that your solution would be the right fit for it.

The second kind of validation I recommend is feedback validation. You go out with your solution and speak to people to understand their problems, whether those problems really exist and whether the solution is a good fit.

The third kind of validation, which is the most important, is evidential validation. A problem may exist, and people might like the solution, but are they going to pay for it? And are they going to come back? That is very important. So, as soon as possible, founders should attempt to sell their solution or offering before actually building it.

Once early evidence emerges, how do you distinguish genuine product-market fit from a short-lived burst of interest, and which customer behaviors do you trust most?

True product-market fit is never static or a one-time activity. True product-market fit means that customers readily accept your solution, willingly pay for it and keep coming back. What you need to know is whether customer acquisition is complemented by customer retention. If people are coming, liking your product, trying your demo and paying for a while, that is a short-lived burst of interest. But if customers are coming back, your overall customer base is gradually increasing and you have retention — and eventually hit the referral or word-of-mouth flywheel — then you really have product-market fit.

When customer feedback challenges a founder’s original thesis, how can they decide whether to refine the product, reposition it or make a more fundamental pivot?

There is a simple way of looking at this. Whenever something is not working, either we are doing the wrong things or we are doing things the wrong way. So, before making a fundamental pivot — assuming that we are doing the wrong things and aiming for a complete or fundamental pivot — we must also ask: Are we doing things the wrong way? This is where structured analysis of different metrics and controlled experiments across different processes, customer groups and stages of the customer lifecycle are important. They give us a lot of answers.

From your work in competitive analysis and go-to-market strategy, how should an early-stage startup interpret competitor activity without losing focus on its own learning from customers?

Competitors give you an indication that the category, the overall solution and the pain point may have market demand. If competitors have paying customers, that also provides some evidence of willingness to pay for their solutions, although it does not automatically validate your startup.

On a modular, granular level, entrepreneurs have to dig deep and understand what they learn for themselves. Just because something has worked for somebody doesn’t mean it’s going to work for you. And if it’s an identical clone, then there’s no moat. There’s no hesitation to switch, and customers may have little incentive to switch from an established alternative.

So it’s very important to combine what you learn from competitors with your understanding of the market and your customers. Figure out those experiments and test whether your solution delivers value, solves an underserved need or gives customers a compelling reason to switch.

How does founder-market fit influence a startup’s ability to adapt, and what should aspiring founders assess about their own capabilities before committing to an opportunity?

Understanding the terrain you’re in is extremely important. A founder is not independent of the startup; the founder is the steering force. Good founder-market fit means understanding the market really well — having access to the right people and customers and understanding their pain points, the competition, the market pricing structure, the supplier side, and the threats and opportunities in a particular market. This gives founders another level of advantage.

Limited knowledge would give founders a narrow view of the startup and the market dynamics. More importantly, if you have access to all the information, you can find different ways to adapt. It’s as simple as this: If you’re in a new city and don’t know the roads, you would typically follow a GPS while driving, and you might suddenly encounter a traffic jam or something like that. But if you’re well-versed in the city’s roadways and have lived there for years, you can navigate those areas quite well, finding new ways, adapting directions and adjusting your route.

Given your experience with business planning, venture funding and investor relationships, what evidence should founders have before raising capital to scale, rather than using fundraising to compensate for unresolved uncertainty?

I will say two things.

First, imagine your early-stage startup as a paper boat — an origami paper boat that can float on water. It is very important to see whether it works. If there is a small leak, the boat will sink. Rather than fixing the leak, if you try to make a Titanic, you will have a huge gaping hole, perhaps the size of a football field, which would be impossible to fix.

Fixing the hole early, when your startup is comparable to a paper boat, is important before you actually scale up. Unit economics should be very important. Founders should have evidence validating:

  • Customers’ willingness to pay

  • Positive contribution margins or a path to making them positive

  • Customer acquisition costs that make sense within the unit economics

  • Retention, repeat purchases and the time required to recover customer acquisition costs

These are the indicators that tell you whether the boat will stay afloat.

The second thing I would say is that startups are experiments. Sometimes your experiment will work, and sometimes it will not. If something is working, double down on it. If something is not working, absolutely avoid it. Before raising capital, founders should be able to demonstrate through actual customer behavior, revenue and repeatable results that their core assumptions are working. They should know what is working, why it is working and whether it can be repeated economically at a larger scale.

Scaling will not solve a problem. It will just amplify your problems.

What is one widely held startup myth that your idea of Evolutionary Entrepreneurship challenges most directly, and what practical habit should founders adopt instead?

We are often told that the startup journey is linear: Come up with a brilliant idea, execute it brilliantly and achieve startup success.

But that rarely happens as planned.

As entrepreneurs, we cannot and should not try to be prophets who figure out the future. At every step, just as a living species develops traits in response to environmental, predatory and evolutionary pressures, startups must adapt to their circumstances.

Simply copying another blueprint or another successful entrepreneur’s journey will not guarantee success.

My suggestion is to conduct a weekly assumptions review: estimates versus reality, expectations versus what actually happened. Based on that, identify what needs to change.

Over time, these small experiments shape the direction of the business. That, to me, is Evolutionary Entrepreneurship in practice.

Thanks for sharing your knowledge and expertise. Is there anything else you'd like to add?

You know, we have seen multiple definitions of entrepreneurship. For me, entrepreneurship is an experiment. An idea is a hypothesis. A new strategy is a hypothesis. An entrepreneur’s responsibility is to find the quickest and cheapest way to prove that hypothesis. In that process, if we can prove it right, then we have a potentially good business to look into. If it does not work, then either we are doing the wrong things or we are doing things the wrong way.

If we are doing things the wrong way, we can tweak, adjust and figure out how to make it work. But if we are doing the wrong things, then we should be emotionally detached from that idea completely, and we should dump it. We should not, as entrepreneurs, be emotionally involved with the startup idea. We should treat it as an experiment, just as scientists treat an experiment. If an experiment fails, they continue with another experiment. A startup idea or a startup venture should not be an entrepreneur’s identity.

Throughout the journey, we have to understand that we will never know the path in advance. We’ll never be able to connect the dots looking forward. We will go through the journey, respond to pressures, respond to the market, respond to changes and adapt continuously to try to stay ahead of the curve. And this is the entire concept of what I call Evolutionary Entrepreneurship.

About the expert
Arnab Ray

Arnab RayEntrepreneur, Mentor, Investor, Speaker, Author at ArnabArray.com

Disclosure: I am the author of Survival of the Smartest: Startups through the Lens of Evolution, which is being published by Bloomsbury. I have no other commercial, affiliate, or paid relationships related to the companies, products, or links mentioned in my responses.

This content is for informational purposes only and should not be considered financial or investment advice.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.
Hardwood Flooring: Six Solid Choices for Your Home

(NewsUSA) - When it comes to home flooring, solid American Hardwoods™ have been our gold standard since the nation’s founding—and they still are. Few materials can match the durability of oak, walnut, maple, ash, and other favorite species, which can be sanded and refinished for decades, outlasting kids, pets, foot traffic, and trends—and somehow looking better for it. They’re also remarkably practical, available in multiple widths, grades, and finishes, and easy to install. “American hardwoods are grown, harvested, and milled right here, giving architects and builders a reliable, high-quality supply,” notes Ian Faight of the American Hardwood Information Center. “Nothing rivals hardwood’s warmth and natural variation, and as a low-emission, renewable resource, it supports healthier interiors and everyday well-being.” Here are six examples of what it can do for your home.
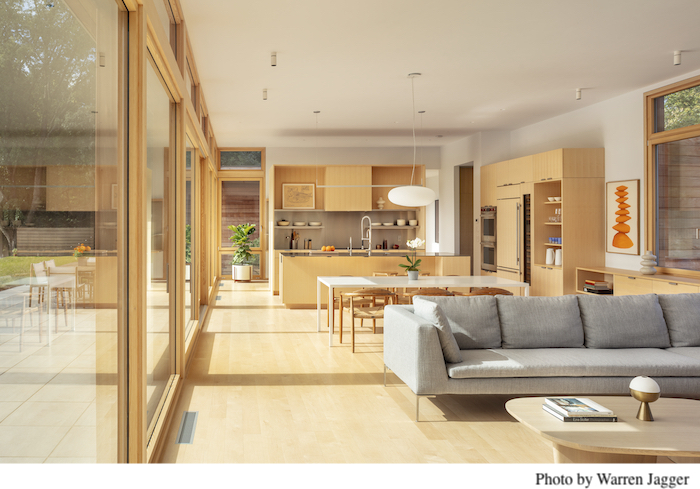
In East Greenwich, Rhode Island, this low-slung modern home by Estes Twombly + Titrington Architects blends into its riverside setting. Inside, hard white maple runs underfoot through the kitchen, dining, and living area—an expanse of 5-inch-wide boards from Vermont Plank Flooring, finished with the company’s Killington Peak stain, which draws out the wood’s warm, golden-brown tones. Clear-finished maple window frames, trim, and cabinetry continue the material palette, grounding a light-filled, sustainably minded interior. 

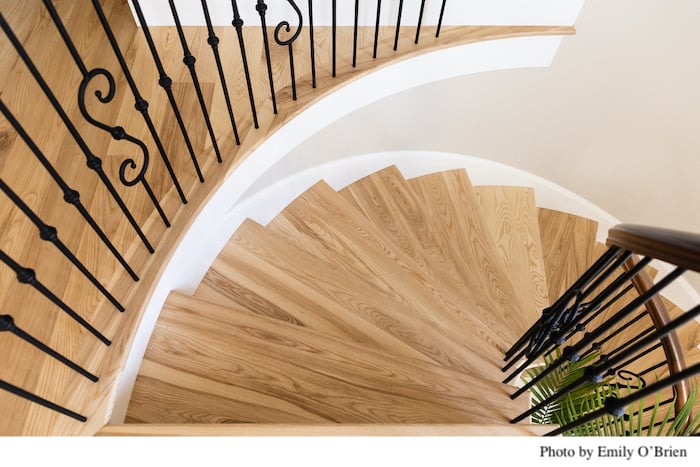
Circled by a delicate wrought-iron balustrade, a flight of select-grade ash treads winds gracefully up the custom spiral stair in a new shingle-style house by Arnold Design Group in Charlestown, Rhode Island. The light-toned wood from Vermont Plank Flooring gives the traditional architectural element a clean, modern look—one that extends to the landing, which comprises 7-inch-wide boards in the same wood, some laid in a herringbone pattern with walnut accent borders for added visual interest. A clear, low-sheen Craftsbury finish plays up ash’s naturally pale, subtly striped grain throughout. 

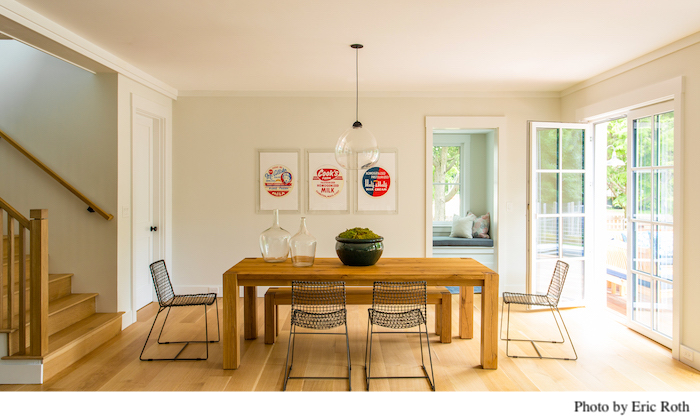
Architect Stephanie Horowitz of ZeroEnergy Design used old-growth white oak, quartersawn for extra stability and a distinctive ray-fleck grain, for the flooring in a house in Wellesley, Massachusetts, constructed to rigorous green-building standards. The dining room’s solid white-oak table, left with its natural splits and knots intact, echoes the floor’s warm tone underfoot, while wire chairs and vintage milk-bottle prints keep the look from feeling precious. True to the house’s eco-minded design, the flooring is not covered by rugs or carpet, which Horowitz avoids as sources of dust and allergens. 

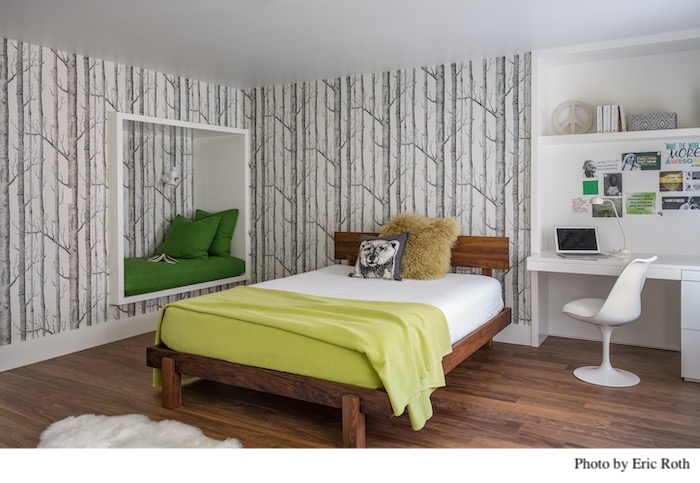
In a 19th-century Boston townhouse renovated by Stern McCafferty Architecture + Interiors, roughly 4,000 square feet of select-grade walnut from Vermont Plank Flooring runs throughout, including this child’s bedroom, where a built-in daybed nook is wrapped in birch-tree wallpaper. Milled in 6-inch-wide planks and finished on-site with Hartland—a water-based, satin-sheen treatment—the wood comes from black walnut trees, slow-growing natives of the eastern U.S. prized for their fine grain and rich, chocolate-brown heartwood. The flooring honors the home’s history while giving the interior a cleaner, more contemporary feel. 

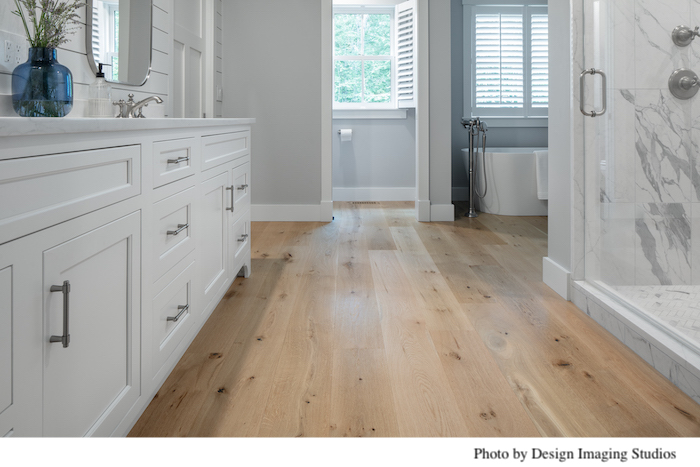
In a whole-house renovation in Dighton, Massachusetts, natural character-grade white oak from Hull Forest Products extends into unexpected territory: the primary bathroom, where 8-inch, live-sawn planks run past the vanity toward a freestanding tub and glass shower. It’s a bold choice, but a sound one—white oak's tight, tyloses-blocked cell structure resists moisture better than many woods, and its density and dimensional stability help it withstand humidity and heavy foot traffic. Even so, area rugs and prompt spill cleanup remain essential. Finished on-site with clear, water-based polyurethane, the reward is underfoot warmth and beauty nothing else can match. 

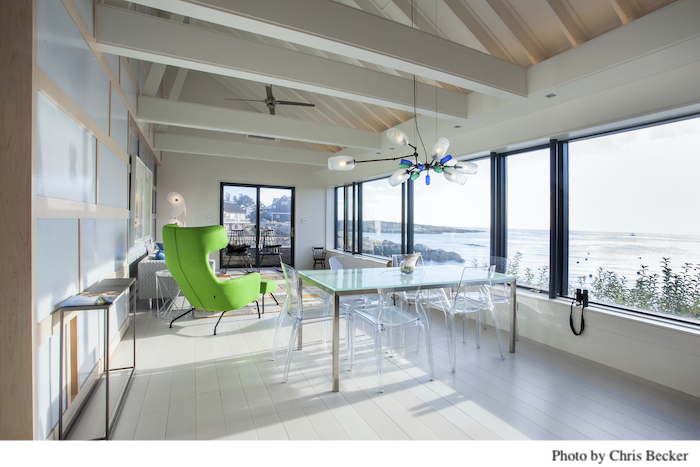
On a Rockport, Massachusetts, peninsula, Ruhl Studio Architects raised an existing house on concrete pilings—both to clear flood requirements and to give the upper level unbeatable ocean vistas. Red oak from Vermont Plank Flooring, laid in 6-inch-wide boards and finished with low-sheen Waltham stain for its warm white overtones, gives the open kitchen, dining, and living space a light, airy foundation. Designed for three generations under one roof, the house pairs the flooring with white-painted poplar walls and steel stairs for a clean, resilient backdrop to the million-dollar view. 

Visit www.hardwoodinfo.com for more about using American hardwoods in your home.

Holiday sellers favor clearer value over bigger discounts, business owners say

Holiday sellers favor clearer value over bigger discounts, business owners say

(Featured) - Six retail and e-commerce leaders converge on transparent, predictable offers, though some create bundles while another raises prices.

Edited by Jenn Moon, Editor at Featured News · Roundup by Featured · Nov 10, 2026

Black Friday 2026 sales had already begun by November 5, The Buffalo News reported, putting holiday promotions in front of shoppers weeks before the traditional shopping rush.

Business owners share specific changes they made to holiday pricing or promotions for shoppers wary of discounts.

Roundups

Chloe ClarkFounder, Simply Sage Dog Treats · Atlanta, Georgia

We use a low flat-fee shipping strategy; temporary peak-season rate increases concern us, particularly during the holiday season. However, in our experience, carriers have moved away from traditional rate sheets and now use dynamic pricing models, with shipping rates changing multiple times per week.

I've noticed these increases affecting online shoppers, especially when purchasing lower-priced items under $20. In some cases, I've seen shipping costs that are half the price of the item or equal to the item’s purchase price. Customers may notice that shipping rates fluctuate from week to week and month to month.

With the current economic conditions and ongoing inflation, I've noticed customers are paying closer attention to the total cost of a purchase, including the product price, shipping, and additional fees, and comparing their options before completing an order.

In response, we implemented a low flat shipping fee of $6.50 on all purchases, with the option for customers to pay a higher rate for faster delivery. In our experience, this approach has reduced cart abandonment caused by unusually high shipping charges. Customers know exactly what they will pay for standard shipping, regardless of their location. The flat-fee model is also significantly more sustainable for our business than offering free shipping.

Amit JhalaniFounder, True Sanity · New York, New York

In my experience, prices in jewelry are often artificially inflated just so they can be discounted. We show actual costs, and these are true costs, not inflated figures. If we do a sale, it comes from our margin, not from the consumer.

What we changed: We created something called the Transparency Manifest, with our protocol fee, where everything is disclosed. Every product page shows what the gold, the stones, the labor and the shipping actually cost, plus our protocol fee, which is what we make.

The difference, from what I've observed, is that people are curious. I've noticed they are spending more time on the site, playing around with it. We hope it will eventually lead to conversion and trust. We did this just about two months ago, so we are only starting to see the fruits.

Ramy GafniFounder, RAMY Cosmetics · New York, New York

What I’m doing differently this holiday season is I’m offering holiday-themed, limited-edition value sets of existing popular products. For example, the Sleigh Brows kit: $64.95 against a $112.94 stated value — the kit is the promo; nothing inside it is discounted on its own.

I’m also offering a free gift with every order, with no minimum purchase.

I often offer promotions like 20% or 30% off, but I wanted to offer a really great holiday set that offers a more enticing value.

Conor SmartDirector, Arklavo · Uk

Rather than trying to one-up everyone with increasingly ridiculous Black Friday deals (starting weeks early), I took away a promotion this year at our custom-embroidered T-shirt, hoodie and polo business.

Rather than layering on even more promotions, coupons, sitewide sales, etc., this year I've opted to highlight our one consistent discount code for 15% off, in March, in November, whenever! There is no minimum order required, and I offer free shipping on orders over $150, plus free logo previews before production.

Especially with custom products, I've noticed that our customers tend to be a bit skeptical, so instead of adding on more promotions and eye-candy (countdown clocks, blinking banners), I'm opting for simplicity and consistency. Rather than a flurry of promotions with constantly changing discounts, I'm banking on our customers appreciating (and trusting) one consistent discount. After all, who really believes "up to 60% off"?

Jason KingFounder, Kelsah · Orlando, Florida

We sell personalized message-card jewelry, and this holiday season I did the opposite of what most stores do. I raised my prices instead of discounting them and don’t plan on lowering them back down.

To me personally, it isn’t a good representation of your store or brand if you don’t believe in your products and the value they bring to someone who is receiving them.

So instead of a huge discount, I made the value something they can see. Almost all of our gifts arrive with a free gift box and message card plus free shipping.

To the right customer, that is real value, and the fact that our products take care of the presentation, gift and the message behind your gift simultaneously actually solves three problems at once. I think our customers really appreciate that.

Todd HarmonFounder, AURA Modern Home · Denver, Colorado

This year we didn't do any holiday promos. That's the difference.

I feel like people are tired of the sales, the marked-down prices, and companies raising their prices and then just offering discounts while calling it a holiday sale. So this year we're going to try no holiday sale. The price will be the same as it is most of the year, always our best price.

What we did change is on the product page. Right next to the price we show that we have free shipping and no tax, and we show that we've been featured in different magazine articles. That helps build some authority with the customer.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

AI assistants cited our pages thousands of times, but few visits were traceable

AI assistants cited our pages thousands of times, but few visits were traceable

(Razvan Luca) - This example from our independent equity research site shows the gap between the citations we can count and the visits we can trace — and why conventional tools make that gap hard to measure.

Edited by Jenn Moon, Editor at Featured News · Nov 9, 2026

During the period of Oct. 9 to Nov. 4, 2026, we received 2,161 citations across our pages from the artificial intelligence (AI) systems tracked by Microsoft's Bing Webmaster Tools. Bing reported 15 clicks to our site from search and chat during this time. These are very different metrics and cannot be interpreted as a rate of citations to visits. The 15 clicks include regular search results, and the AI Performance report does not include any data about clicks. We cannot say how many of the 15 clicks were from AI.

Other research has measured a related effect. A July 2025 study by Pew Research Center looked at how 900 U.S. adults used their browsers in March 2025. If the results included an AI summary from Google, only 8% of visits resulted in a click to a traditional result, compared to 15% where there was no summary. If there was a summary, only 1% of visits resulted in a click to a link in the summary. We can show how often our pages were requested by bots and cited and how few visits we could attribute to AI assistants.

Not all pages were visited

Some AI assistants will crawl the web using bots, like a search engine. Others, such as ChatGPT-User and Claude-User will download a page when requested by the user. Each question can result in multiple downloads. Under our free plan, we use Cloudflare's AI Crawl Control, which identifies bots by their user agent strings.

Between Oct. 9 and Nov. 4, 2026, we received 17,770 requests from OpenAI's bots. Of these, 2,970 were from ChatGPT-User. Over the same period, our web analytics showed 34 visitors from ChatGPT. This means that for every visitor we could attribute to ChatGPT there were approximately 87 requests from ChatGPT-User. This is not a rate of questions to visits.

Anthropic's bots made 13,730 requests during the same period. We had no visitors we could attribute to Claude. In July 2025, Cloudflare analyzed Claude's traffic and found that for every HyperText Markup Language (HTML) page referral there were approximately 70,900 HTML page requests in one week of June 2025. They also noted that the Claude app does not provide any referral information so this number may be inflated. Any visits may have been recorded under the "direct" section of an analytics tool. The numbers we have are not directly comparable as we are comparing bot requests to visitors, whereas Cloudflare is comparing HTML page requests to HTML page referrals. However, they do follow the same trend.

Perplexity's bots made 3,270 requests. We had no visitors we could attribute to Perplexity. We had 21 visitors from Google in our analytics, which were classified as organic search. We cannot say how many of these came from an AI feature.

Different pages were cited

We noticed a difference between the pages most frequently cited in Bing's report and the landing pages of the ChatGPT visitors we could trace. Sixty-six percent of the 2,161 citations we received from Bing were from our three educational guides (intrinsic value, discounted cash flow, and price to earnings ratio). Bing's Citation Share report shows that we received 61% of all the citations Bing displayed for the query "dcf model formula" and 47% on the query "Talval."

Over the same period, we had 34 visitors from ChatGPT. Only one of these landed on an educational page. More than half of these visitors (20) landed on a page tracking the performance of sectors using current market data. Most of the remaining visitors (12) landed on pages based on recent institutional holdings filings. Our hypothesis, based on the data from just one site and two platforms, is that people click through to get information that changes daily and cannot be included in a chat. There may be little reason to click through to a formula that has already been detailed. We have not tested this.

Quick increase in citations

Between Aug. 18 and Sept. 28, we had 886 citations from Bing. This averages to 21 citations per day. Between Oct. 9 and Nov. 4, we had an average of 80 citations per day. This is roughly four times as many.

Not all AI traffic results in a visit

Out of the 8,060 requests we received from Claude-User between Oct. 9 and Nov. 4, 7,210 (89%) did not request a web page. They requested our endpoint for Model Context Protocol. This is an open standard allowing AI assistants to make calls to external tools during a chat. We don't know how many of these were genuine questions and how many were setup calls. Either way, they are just requests and would not show up in our web analytics.

Confusion with tools

The main issue is that our tools don't measure the same things. Microsoft added the AI Performance report in February 2026. This report gives us five metrics, all related to citations. There is no reference to clicks or traffic in the announcement. The search report from Bing doesn't distinguish between web and chat so we cannot see how many of the clicks were from Copilot. A sample of the Ahrefs index of AI answers (checked on Nov. 3) showed that we had 21 citations: 11 from Copilot and 10 from ChatGPT. There were no citations from Google's AI Overviews, Gemini, Perplexity or Grok in that sample. We also made a couple of mistakes.

We almost wrote a headline saying we had 886 citations from Copilot and seven visitors. The 886 citations were from the AI report for Aug. 18 to Sept. 28. The seven visitors were clicks from classic Bing search for a different period. We also ran some tests on our site in September using requests with AI bot names. All of these were blocked. We almost came to the conclusion that we couldn't be seen by AI assistants. In reality, our requests had been blocked by Cloudflare's bot protection. As we were using AI bot names in our requests but they were not coming from the servers of those companies, they were seen as fake. Real bots were still getting through. Between Oct. 9 and Nov. 4, Cloudflare's report shows that 508 megabytes of data were transferred to OpenAI's bots.

What we would look at first

We found a few best practices to help us understand our AI traffic. Compare the same dates across all tools. If you cannot, mention this. Distinguish between live bots (those that download pages when requested) and crawling bots. User-initiated bots can indicate that someone is asking a question. Each question can result in multiple downloads. Treat any AI visitors you can attribute as a minimum. Many apps will not show where they are coming from so their visits may show up as direct traffic. Look at your citation reports by query to see which pages are answering questions on their own. Finally, ensure you know what each report is actually measuring before comparing two numbers.

How we measured

Requests from bots can be found in Cloudflare's AI Crawl Control report (Oct. 9 to Nov. 4, 2026). We downloaded them as daily CSV files from the Metrics tab on Nov. 7, 2026. Our free plan let us select up to 30 days, even though Cloudflare's documentation says the Metrics tab shows 24 hours on free plans. These numbers are estimates from sampled data, so each daily value is a multiple of 10. Under our free plan, bots are identified by their user agent strings. Visitors can be found in Ahrefs Web Analytics (cookieless tool). We had 34 visitors from Oct. 9 to Nov. 4, 2026. We had a breakdown of landing pages for the same dates. Citations and Citation Share can be found in the AI Performance report from Bing Webmaster Tools. This was for Oct. 9 to Nov. 4, 2026. We downloaded the daily citations, queries and cited pages as CSV files and the clicks from Bing's search report for the same dates. Bing states that this is a sample of the data and there is a day or two delay. This is just one young and small site with low search traffic, so it shouldn't be considered typical. We also cannot attribute traffic from AI apps that don't show where they are coming from, so our visitor numbers are a minimum.

Disclosure: We pay for an Ahrefs subscription. We pay Anthropic for application programming interface (API) access, as part of our site uses Claude models. We have run Google Ads campaigns in 2026. We use the free versions of Cloudflare and Bing Webmaster Tools. We have no commercial relationship with OpenAI or Perplexity.

About the author

Razvan Luca

Razvan Luca is the founder of Talval Research, an independent equity research platform that values around 1,000 U.S. and European companies from their filings. He writes about how search engines and AI assistants find, read and cite financial content, as well as the errors in the data.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

D8TAOPS Brings Governed Knowledge to Amazon Quick, Now Generally Available in AWS Marketplace

(Troy Wyatt, Founder and CEO, and Dr. Navid Kalantari, PhD, Chief AI Officer, D8TAOPS) - Built with Mark Relph's team at AWS, the integration lets Quick customers govern the data and the agents behind every answer, inside their own AWS account.

BEAVERTON, Oregon (November 1, 2026) D8TAOPS today announced the general availability of its integration with Amazon Quick, now available in AWS Marketplace. It gives organizations a way to take Quick from its first teams to the whole company while keeping firm control of their data and their agents.

The integration connects D8:Platform to Amazon Quick through a single MCP connection, managed by D8's Agentic Capital Management™ (ACM). People keep working in Quick the way they already do. Beneath them, D8 prepares, reconciles, and governs the enterprise knowledge their questions and agents depend on, and checks every request against the person's role, the data's classification, and their part of the organization. Everything runs inside the customer's own AWS account.

D8TAOPS built the integration with Mark Relph's team at AWS, which asked the company to prove the connection end to end inside Quick before taking it to customers. Dr. Navid Kalantari, PhD, D8TAOPS's Chief AI Officer, led the engineering.

Two halves of the same rollout

Amazon Quick gives an enterprise one place where people and agents ask questions, build automations, and act on what they find. That reach is what makes a company-wide rollout worth doing. It is also why security, compliance, and data leaders want a say once Quick moves past its first teams. Before they sign off, they want to know whose data an agent can see, whether the answers hold up, and who is accountable when an agent acts.

D8TAOPS was built for that conversation. Quick provides the interface and the agents. D8 governs the knowledge beneath them and keeps account of every agent working on it, so the people who approve an enterprise rollout have what they need to say yes.

"Every company we talk to wants Quick in front of all of its people," said Troy Wyatt, Founder and CEO of D8TAOPS. "What slows them down sits underneath: whose data an agent can see, whether two people asking the same question get the same answer, and who answers for an agent once it acts. We built D8 to settle those questions inside the customer's own environment, so the decision to go company-wide gets easier for everyone who has to make it."

Where it applies

The value looks different depending on who is using Quick and what they answer for. A few examples:

Consider a global insurer preparing to open Quick to every business unit. The security architect's first concern is agents. Employees will build them by the thousands. With D8 connected, an agent can still be built in Quick in minutes, but it reaches no governed data, tool, or API until it is registered in Agentic Capital Management™ with an owner, a purpose, and explicit permissions. Every request is checked against the person's role, the data's classification, and their part of the organization, so only what they are entitled to see ever reaches Quick. The rollout gets approved because the guardrails are in place before the first agent goes live.

A regulatory reporting manager at a regional bank has a different concern: her mornings. She asks Quick once for the overnight exceptions summary she used to assemble by hand. D8 turns the request into a plan she approves and a scheduled pipeline her data team reviews, running in the bank's own AWS account. The summary is waiting every weekday, and when an examiner asks how a number was produced, the record already exists.

Some answers depend on getting the data to agree with itself. An upstream oil and gas operator may track the same well under three different identifiers across its historian, maintenance, and inspection systems. D8 reconciles them in a knowledge graph, so when operations staff ask Quick which wells showed pressure anomalies after a pump replacement, they get one answer they can trace to its sources. At an automotive supplier, the earliest sign of a failure pattern often lives in technicians' free-text service notes. D8 turns those notes into knowledge Quick can reason over, tied to the right part numbers, so the warranty team sees the pattern before it reaches the claim counts.

In healthcare, the stakes sit with protected health information. A denials specialist working through rejected claims can ask Quick why a claim was denied and what the payer's policy says, and get the policy citation in the same answer. D8 applies access policy before anything is retrieved, so protected health information reaches Quick only for people whose role allows it. That is what lets a health system open Quick to its entire revenue cycle team.

"Customers, including Financial Services Institutions, are implementing Amazon Quick for multiple employee types, which include different roles, responsibilities, and varying levels of access to sensitive data," said Jeff Axelrad, Director Governance, Risk, & Compliance, AWS Financial Services. "D8TAOPS enables them a way to enforce that policy inside their own AWS environment."

One connection, eight agents behind it

"To someone working in Quick, this is one connection," said Dr. Navid Kalantari, PhD, Chief AI Officer at D8TAOPS. "Behind it, eight D8 agents bring the data in, clean it, catalog it, and enforce policy under the permissions of the person asking. Then they build the infrastructure that keeps it running on a schedule, in the customer's own account, and every step leaves a record. In testing, a plain-language request in Quick became a governed, cataloged dataset in about 23 minutes, with a person approving each stage."

That reflects the principle D8TAOPS builds on: govern the knowledge, not just the agents. When the knowledge underneath Quick is reconciled, described, and governed, every agent built on top of it starts from solid ground.

Available now

D8:Platform for Amazon Quick is generally available today in AWS Marketplace: https://aws.amazon.com/marketplace/pp/prodview-hf2wfrtihdqya?sr=0-1&ref_=ucaf&applicationId=AWSMPContessa. It works alongside an existing Amazon Quick subscription, deploys into the customer's AWS account, and Quick users connect to it without changing how they work.

"Our customers chose AWS and Amazon Quick for good reasons, and our role is to make that choice go further," said Jared Cooper, Director of Partnerships and Marketing at D8TAOPS. "Through AWS Marketplace, D8 arrives the way the rest of their AWS investment does: through procurement they already use, on the same AWS bill, and into an account they control. What they have built becomes the foundation for what comes next."

About D8TAOPS

D8TAOPS builds the governed knowledge layer for enterprise AI. Its platform unifies, secures, and operationalizes enterprise data inside the customer's own environment, and its Agentic Capital Management™ framework holds every agent accountable for what it reaches and what it does. D8TAOPS is headquartered in Beaverton, Oregon. Learn more at d8taops.com.

Interview with Ankit Sarawagi, Curator, CFO Matrix

Interview with Ankit Sarawagi, Curator, CFO Matrix

(Featured) - Sarawagi explains how to track collections, runway and working capital, build flexible forecasts, and make funding answer specific business questions.
Edited by Jenn Moon, Editor at Featured News · Nov 7, 2026

As Curator at CFO Matrix, with experience across accounting, finance, and fundraising, how would you describe the perspective you bring to helping founders understand cash?

Cash is where a founder’s real position shows up. Revenue reflects sales; cash is the money the business has actually collected. I start with the collection cycle — days sales outstanding, or the average time it takes a sale to turn into cash. In one SaaS company, it ran near 90 days while the team celebrated top-line growth. Bringing it to roughly 40 days cut about 50 days off that cycle, releasing a one-time slug of working capital equal to around 50 days of credit sales. The exact figure tracks the sales run rate; the mechanism is that cash sitting in receivables returns to the business. I make cash visible weekly so founders read it as a leading signal, well ahead of any month-end surprise.

What career experiences led you from hands-on financial disciplines such as accounting, reconciliation, and financial analysis to your current work as a curator?

I began by ensuring that the financial statements contained the correct numbers. This typically involved months of reconciling and closing the books. While this work is important, it is typically backward-looking. Other aspects of my role moved me toward looking to the future. More specifically, co-founders started to approach me for input on forward-looking questions. These included elements of the business, such as financial projections and business economics. Ultimately, these aspects of my role focused on using the skills and experience I developed in finance and accounting to help business leaders raise capital and make key strategic decisions. This has been the case at multiple fast-growing businesses I have worked for. Recently, I have been involved in Series A and Series B financings and related discussions with founders. Overall, the work I do now helps founders look to the future and maintain clarity as they steer their businesses.

From your experience reviewing businesses and their financials, what is the most important distinction founders should make between revenue, profit, and cash in the bank?

Treating these three aspects of a business, particularly revenue and profit, interchangeably can be harmful. Revenue and profit are accounting figures that illustrate a business’s financial status. Cash is real money. A business may have good revenue and profit but no cash. Cash is usually tied up in business inventory and/or receivables. The business may not be able to pay its employees and may have to borrow money to do so. I once evaluated a direct-to-consumer (D2C) company that, from an accounting perspective, showed profits and revenue but could not pay its employees because cash was tied up in inventory and accounts receivable. A founder must keep these three aspects, particularly cash, under control.

You have argued that live cash-flow data can reveal more than historical tax returns; what cash signals should a founder monitor each week to understand the current health of the business?

A weekly view provides more timely insight into your business' cash position than a historical tax return. I expect founders to track four signs:

  • Cash collections: Was the sale real?

  • The cash balance in relation to committed outflows.

  • Runway: Do you have enough cash to last until the next financing?

  • Aging receivables: When do you expect to be paid?

Cash collections focus founders on the signs they should use to manage the business. Each week, founders learn to use cash collections to steer the business.

What is one early warning sign in accounts receivable or accounts payable that founders often overlook until it becomes a cash problem?

What I watch for is an upward trend in the average collection period, coupled with rising sales. Founders focus on the positive — rising sales — and overlook that the collection period is increasing. The longer the collection period, the more of the company’s capital is funding customers rather than the business itself. The mirror image on the payables side is the company stretching the terms it has negotiated with its own suppliers to stay liquid. It can do this only for a limited time before those relationships become strained. I like to look at the collection period as a trend over several months rather than month to month. Viewed that way, it usually shows where collections are heading a few weeks in advance.

In capital-intensive sectors such as computer hardware, how have you seen inventory, supplier terms, or production timelines reshape a founder’s cash-planning decisions?

In any inventory-led business, cash planning turns on timing. I have seen this most closely in D2C, where the mechanics mirror what capital-heavy sectors face. A founder commits cash to stock weeks or months before a customer pays, so the cash conversion cycle governs how fast the business can fund its own growth from internal cash. Shortening the time inventory is held or negotiating longer terms with suppliers releases cash that was tied up in the cycle. That cycle sets a ceiling on self-funded growth rather than on profit; profit follows from margin, while the cycle decides how quickly cash recycles. A founder can still grow faster by raising capital or improving terms. The point is to plan against the cycle so a large growth order becomes a funded decision rather than a cash surprise.

Based on your financial-planning and forecasting experience, what is a practical way for a founder to build a cash forecast that remains useful when assumptions change?

Have flexibility in your forecast. Known deviations from your assumptions should not require a complete rebuild of your financial model. Founders should identify and articulate their core assumptions as part of their cash view. Core assumptions may include collection dates, burn rate, and outflow assumptions. These assumptions should be documented in such a way that if the market changes or the assumptions evolve, the core of the model remains intact. The remaining components of the model should be flexible enough to accommodate evolving core assumptions. Founders should also evaluate cash flow in the context of different scenarios, such as best-case and worst-case scenarios. A forecast should reflect management’s judgment based on the latest information and provide insight into potential cash flow issues before they occur. A published forecast should be reviewed against actual cash flow to reflect and update management’s understanding of the underlying business.

You have noted that funding should buy time to test a critical assumption rather than simply fuel spending; how can founders decide whether a planned expense is truly extending the company’s learning or merely increasing burn?

I ask founders to articulate the question an expense is intended to answer. Money should be spent to answer questions, and answers should be used to make decisions.

There are questions related to the price at which a company is acquiring customers, the longevity of a market, and a company’s product and its ability to retain customers. The outcome of an expense should answer a question related to one of these areas.

I require founders to state the question and the answer that would negate the assumption. The outcome of the expense should allow the founder to learn something that justifies answering the question.

I also believe that there should be a time constraint on each expense. A budget should reflect the questions a company has and the answers it is seeking.

What is one cash-management habit you wish every founder adopted before pursuing outside financing, and how has that habit made a meaningful difference in a real business situation?

The habit is knowing your cash runway down to the week and watching it as closely as sales. A founder who can state how many weeks of cash remain at the current burn rate can open a raise with room to spare, on their own timing rather than against a near-empty account. I saw this in a SaaS business where collections ran near 90 days and cash felt perpetually tight. Once the founder tracked runway weekly and we brought collections to around 40 days, the pressure eased, and the next round happened on a planned schedule. Discipline of that kind tends to build investor confidence, since a clear command of cash signals a founder who understands the business. It strengthens credibility and the founder’s position going into a raise, which supports the conversation on terms.

Thanks for sharing your knowledge and expertise. Is there anything else you'd like to add?

I think we have covered it all. Thanks for the conversation.

About the expert

Ankit Sarawagi

Ankit SarawagiCurator at CFO Matrix

This content is for informational purposes only and should not be considered financial or investment advice.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

Interview with Vincent Loforti, CEO, Anchorvia Financial

Interview with Vincent Loforti, CEO, Anchorvia Financial

(Featured) - The interview covers payment schedules, fees, documentation and credit profiles across advances, term loans, lines of credit, SBA loans and equipment financing.
Edited by Jenn Moon, Editor at Featured News · Nov 7, 2026

As CEO of Anchorvia Financial, how does your experience in small-business funding and corporate finance shape the way you advise owners on choosing capital?

When I advise business owners on choosing capital, I start by asking questions. The first one is always, “What do you need the money for?” Then I help them figure out whether it actually makes sense for them and their business. I really do care about the health of my clients and their businesses.

What path led you from sales and business development into the underwriting and financial-analysis side of small-business lending?

When I first got into the business, I was primarily focused on sales and getting deals funded. In all honesty, when you're a young guy barely getting by, your first priority is usually making money. As I got further into the business, I realized that if I really wanted to be an expert at what I do, I needed to understand underwriting and how funders actually evaluate risk. It helps us get more deals approved, saves our funding partners time and, more importantly, allows me to do a better job for the business owners we're working with.

When a business owner first comes to you needing capital, how do you help them determine whether the need is truly short-term working capital or a longer-term investment?

Take a construction company as an example. Say they just landed a new build, but they don't have the upfront capital to buy materials or cover payroll for the first 15, 30, or 60 days before the client's first payment comes in. That's a short-term need. If they need to buy a new truck, a large piece of equipment or rent a new building, that's long-term. That's definitely not something you want to use a cash advance for, because there are other options. Unfortunately, a lot of small business owners either don't know what those options are or don't qualify for them yet. They need a qualified professional to walk them through what's available, then coach them on how to get into a position to qualify for a better product.

Based on the deals you have reviewed, what should an owner compare beyond the amount funded when weighing a merchant cash advance against a term loan?

A merchant cash advance is generally structured as a purchase of future receivables rather than a traditional loan. You get money now, and the provider takes a set amount out of your deposits until it’s paid.

The pricing is a factor rate, not an interest rate or an annual percentage rate (APR). Those aren’t apples to apples. A factor rate is the total amount to be repaid divided by the amount advanced, before fees. It does not annualize the cost the way a loan APR does. So, if someone quotes you a factor rate next to a loan rate, you’re comparing two different measuring sticks.

Here’s how I walk an owner through a fair comparison. First, get the net amount you actually receive after every fee. Then, get the total you pay back in dollars. Then, find out how long the money stays out and how often the payment hits. A shorter payback usually means a bigger daily or weekly hit. A longer payback usually means a smaller hit but more total days with money leaving the account. Put those next to a term loan the same way: net funded, total payback, payment size and schedule. Then decide which one the business can actually live with.

The ranges I use below are based on what I typically see in the files I work with, not on a published market survey. Every funder is different, and these figures change.

We’ll use $100,000 because it’s easy math. Businesses with strong financials and strong credit might see a factor rate of around 1.12 to 1.29. At 1.29, the total payback is $129,000. Fees usually come out of the funding, so the owner might net closer to $97,000, not the full $100,000.

Weaker financials, a low average daily balance, overdrafts, uneven revenue, or credit in the mid-500s to mid-600s with maxed-out cards or collections often result in a factor rate closer to 1.37 to 1.49. At 1.49, the payback is $149,000, and fees are often higher, so the net funding might be more like $92,000 to $95,000.

None of that means an advance is right just because the owner needs money. Sometimes the better move is to wait, clean up the books and come back later.

How do payment frequency and cash-flow variability influence whether a line of credit, term loan, or merchant cash advance is a workable fit for a business?

It comes down to whether the business can make the payments without choking, especially in a slow month.

I review bank statements digitally for every file. Deposit patterns matter. A restaurant that receives money every day can often handle a daily or weekly pull. A contractor who gets paid once or twice a month is different. Those pulls keep coming on the empty days, and that’s when payroll and suppliers get tight.

Here’s how I judge affordability: Take the worst month from the last six and subtract the total proposed financing payments for that month. What’s left still has to cover rent, payroll, suppliers and the basics. If it doesn’t, it’s the wrong fit, even if an average month looks fine. Revenue swings. You lose a client, a truck breaks down or a job gets delayed. The payment still comes out.

If the owner doesn’t qualify for a term loan or a line of credit, coaching on setting money aside for those pulls can help. But setting money aside only works if the worst-month math still clears.

In a hardship, some providers will pause or reduce payments for a stretch if you call them early. That depends entirely on the provider and the agreement. It is not guaranteed, and I never promise it. Stacking advances makes the cash-flow squeeze worse. I’ve seen owners get into a bad spot when new pulls start covering old ones. There’s no magic number that fits every business. The risk goes up as more daily or weekly payments stack on the same deposits.

What financial records or operating metrics do you look for when assessing whether an owner may be ready for an SBA loan rather than faster alternative financing?

For a Small Business Administration (SBA) loan, cash flow is often central. Lenders want to know that the business can repay, and cash-flow analysis is a big part of that. Tax returns and credit still matter a lot in the files I see, as do the rest of the financials.

In my experience over 13-plus years in commercial finance, many owners write off as much as they can. That’s between them and their accountant. But when the returns show very little profit, it can be a hard conversation, even when the bank account looks healthier day to day. Lenders weigh these pieces differently. I’ve sent the same file to five lenders with similar guidelines and received two approvals and three declines.

On credit, the score makes a difference, but the profile matters most. Someone with a high score and only a year or two of history on a couple of cards can have a harder time than someone with a lower score, an older mortgage and cards they’ve paid on for years. That doesn’t mean the person with the high score won’t qualify. Every lender is different.

From your experience with equipment loans, when does financing equipment make more sense than using a general-purpose loan or line of credit?

A line of credit is great because you can use it for pretty much anything. If you’re able to finance the equipment directly, that leaves your line open in case you need it. Depending on the deal, equipment financing rates can be in the same range as a line of credit or a term loan. A lot of times, it makes sense to finance the equipment directly, but it really depends on the deal and on who the funder or lender is. Rates and underwriting criteria change all the time across the board. What makes sense for one business may not make sense for another, even in the same industry.

What are the most common mistakes you see owners make when comparing funding offers, and what simple process can they use to avoid them?

They go with the first option presented to them. Marketing is very aggressive in the financial world, and a lot of business owners don't understand what options are truly out there for them.

The best way to compare offers is to be patient. Every funder and every lender has different underwriting guidelines, so get offers from more than one. One might come back in 24 to 48 hours, but the fastest deal isn't always the best. When you compare, look at the rate, the total payback, the fees and the payment. One deal might cost more overall but have a lower payment, and that can be better for cash flow. Or it's the other way around. A lower payment isn't always what matters most. If the owner can handle a higher payment, the lower total cost may be more important.

The other mistake merchants usually make is waiting until they absolutely need the money and the business is already in trouble before they look for help. That's actually the worst time to try to get funding.

If an owner wants to improve both their funding options and the advice they receive from lenders or advisors, what should they do in the next 90 days to strengthen their financial profile?

They should know what their credit looks like and what's on their credit report. They should have at least six months of business bank statements. If they have profit and loss statements, balance sheets, accounts receivable (AR) and accounts payable (AP) reports and tax returns, that's great. For a merchant cash advance, you typically just need your bank statements. For anything else, like a line of credit, a term loan or especially an SBA loan, you're going to need full financial documents, kind of like when you're buying a house.

If you're looking for long-term financing and don't need a quick fix, one of the very first things to do is pull your three-bureau credit report and check it for errors. Sometimes there's an account or a collection on there that doesn't belong to you, and you want that removed. Get your finances in order, too. Keep your bank statements clean. If you're constantly overdrafting, find a way to stop. You want everything to look as good as possible, and the exact steps depend on what you're going after.

If you need cash quickly, you're not going to have 90 days to prepare. But if you're buying a building or financing heavy equipment—something you don't need tomorrow or the next day—you can take the time to get your credit and finances ready. Have all your financial reports in order, because once you get into better products like equipment financing, term loans and lines of credit, lenders are going to want to see more than your bank statements.

Thanks for sharing your knowledge and expertise. Is there anything else you'd like to add?

Pay down your credit cards. Make sure your bank account balances are healthy. Don’t overdraft your account, and don’t use your business bank account as your personal account. Try to keep your revenue relatively consistent.

About the expert

Vincent Loforti

Vincent LofortiCEO at Anchorvia Financial

Disclosure: I am the CEO of Anchorvia Financial, a small-business financing brokerage referenced in these answers.

This content is for informational purposes only and should not be considered financial or investment advice.

This story was produced by Featured and republished with permission. Experts featured here are members of Connectively, Featured's expert network.

Subscribe to Business